Zopa loans are unsecured personal loans from Zopa Bank. Zopa says you can borrow between £1,000 and £50,000 over one to seven years. You can check your personal rate with a soft credit search, which does not affect your credit score. A hard search only happens if you go on to apply in full and get approved. Before you apply, compare the personal APR you are offered, the total amount repayable and the early repayment terms with what other lenders would give you.
This guide covers how the rate check works, who qualifies, what affects the rate you are offered, and how to set a Zopa quote against other lenders such as Tesco Bank and Barclays.
How do Zopa loans work?
With a Zopa personal loan you borrow a fixed amount, then pay it back in fixed monthly instalments over a term you choose. The interest rate stays the same for the whole term, so your repayments do not change. The loan is unsecured, which means it is not tied to your home or car. Your rate depends on your circumstances and credit history.
According to Zopa's help pages, loans currently run from £1,000 to £50,000, on terms of one to seven years. Some older comparison sites still show lower maximums. Zopa's own site is the reliable place to check the current limits.
How does the Zopa rate check work?
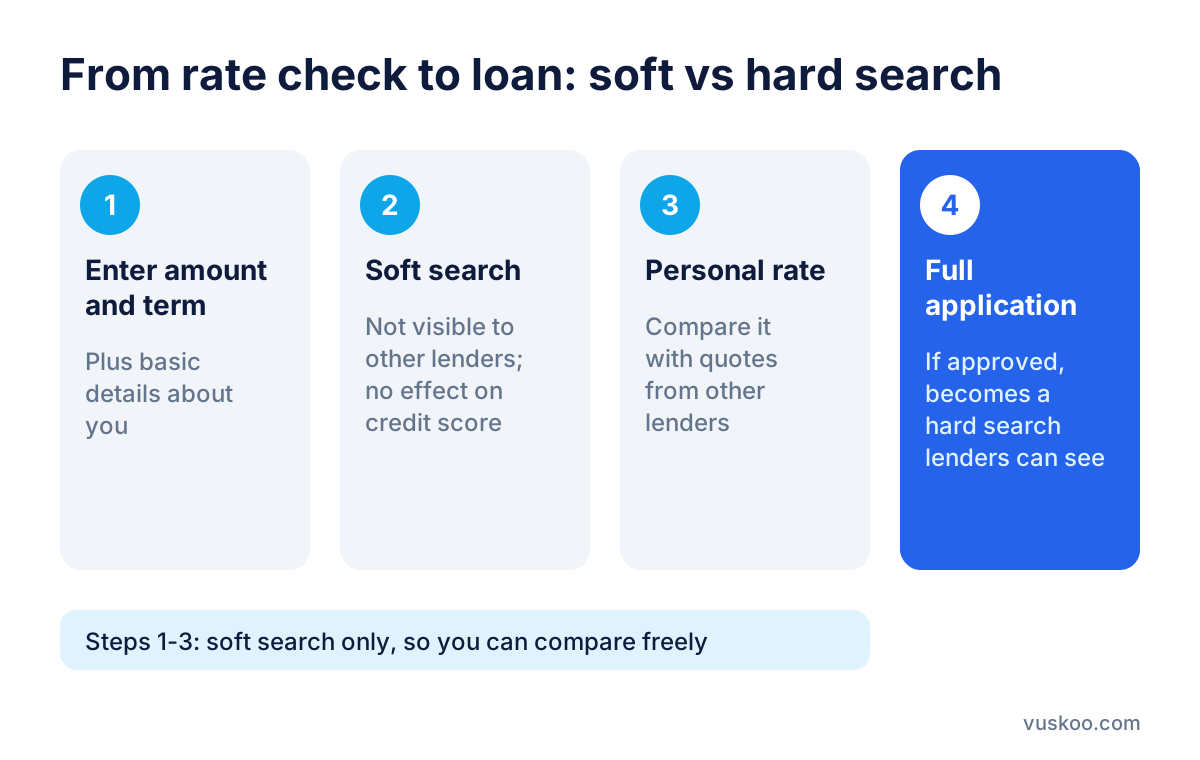
The first step is a rate check, sometimes called an eligibility check. You enter how much you want to borrow, how long you want to repay it over and some details about yourself. Zopa then runs a soft credit search and shows you a personalised rate.
- Soft search: Only you can see it on your credit file. Other lenders cannot see it, and it does not affect your credit score.
- Personalised quote: The rate is based on the amount and term you entered. If you change either one, the rate may change too.
- Full application: If you decide to go ahead and are approved, Zopa turns the soft search into a hard search. Other lenders can see hard searches.
This is why checking your rate first makes sense. You see a real figure for your situation before anything shows up for other lenders. Several hard searches close together can make lenders more cautious, so try to make a full application only when you have settled on an offer.
Who qualifies for a Zopa loan?
At the time of writing, Zopa says applicants need to:
- be aged 20 or over
- live in the UK and have at least one year of UK address history
- earn at least £12,000 a year before tax
- be employed, self-employed or retired with a pension income
- have a credit history with a good record of repayments
Meeting these criteria does not mean you will be approved, and it does not decide your rate. They are the minimum you need for Zopa to consider an application. The rate check is how you find out what you would actually be offered.
What affects the rate you are offered?
Personal loan rates are based on risk, so two people asking for the same amount can be offered different rates. The main factors are:
- Credit history: missed payments, defaults or County Court Judgments make lenders more cautious. A long record of on-time payments works in your favour.
- Income and outgoings: lenders check whether the monthly repayment fits your budget after your existing commitments.
- Existing debt: high balances on credit cards or other loans compared with your income can push your rate up.
- Loan amount and term: rates often differ by borrowing band, so a slightly different amount can change the rate you are quoted.
- Electoral roll and address history: being registered at your current address helps lenders confirm who you are.
How can you prepare before checking?
- Check your credit report with the main credit reference agencies and get any errors corrected.
- Register on the electoral roll at your current address.
- Pay down revolving balances if you can, and avoid new credit applications in the weeks before you apply.
- Work out a monthly repayment you can afford comfortably, rather than the most you could stretch to.
What should you compare before you apply for a Zopa loan?
The representative APR in adverts only has to be offered to a share of successful applicants. The figure that matters to you is your personal APR, which you see after a soft-search check. You can get personalised quotes from several lenders, including Zopa, Tesco Bank and Barclays, and then compare them side by side. The live offer boxes on this page show the current headline rates.
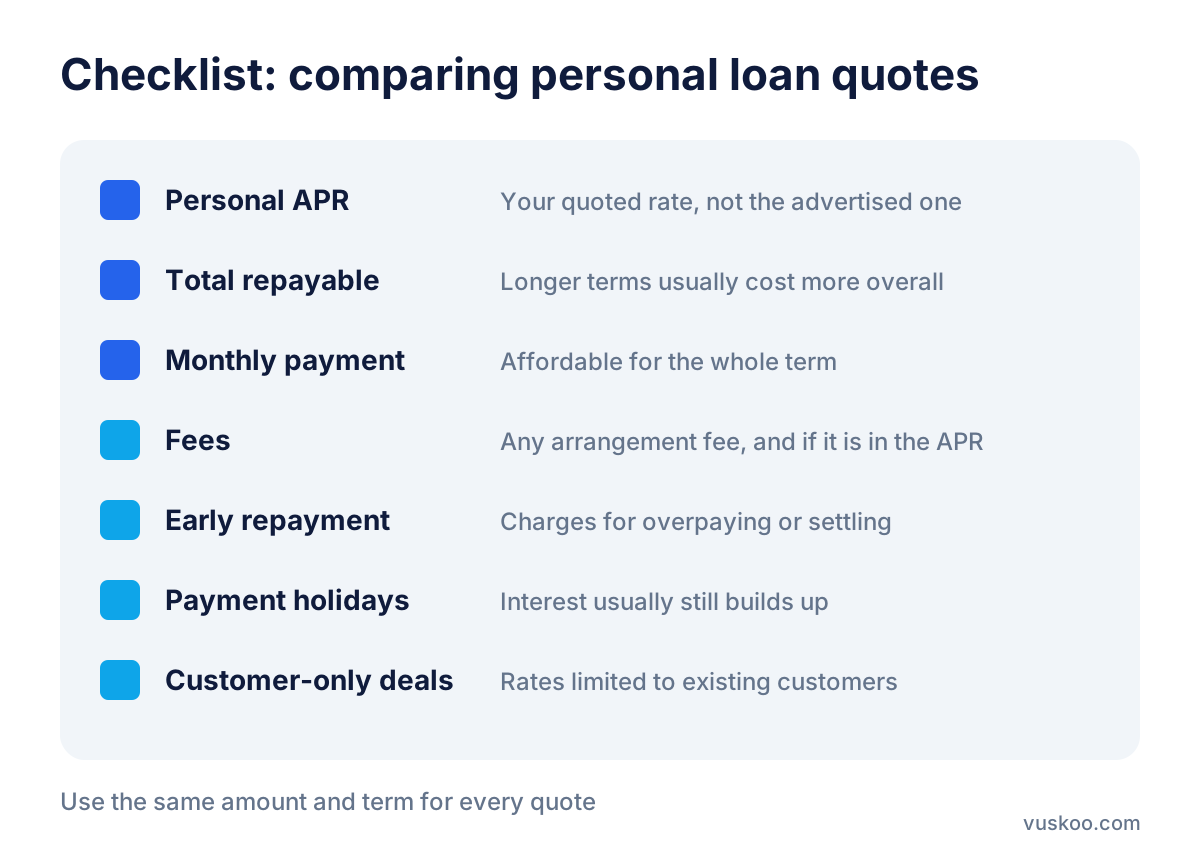
When you compare quotes, look at:
- Personal APR: the yearly cost including interest and any compulsory fees. It is the fairest single figure for comparing loans.
- Total amount repayable: a longer term lowers your monthly payment but usually means paying more interest overall.
- Monthly repayment: check it fits your budget for the whole term.
- Fees: check whether there is any arrangement or borrowing fee, and whether it is included in the APR.
- Early repayment terms: what you would pay to clear the loan early or make large overpayments.
- Payment holidays or deferred starts: these can sound useful, but interest usually builds up in the meantime.
- Existing customer access: some banks only offer certain rates or loan sizes to existing current account or credit card customers, so check whether this applies to you.
Can you repay a Zopa loan early?
Yes. UK consumer credit rules give you the right to repay a personal loan early, either in full or in part. Lenders can charge a limited amount of compensation for this. The amount is capped by law and depends on how long your loan has left to run.
Zopa's help pages say that for loans taken out after 7 September 2022, an early repayment charge may apply in some cases. This includes making a one-off payment of £1,000 or more, or repaying 95% or more of the outstanding balance. The app shows the exact charge before you confirm a payment. If you think you might clear the loan early, for example when a bonus comes in or a property sale completes, check these terms against other lenders' terms, not just the APR.
Is a Zopa loan the right choice for you?
It depends on the quote you get and what you need the loan for. A personal loan suits a planned one-off cost with a fixed repayment schedule, such as home improvements, a car or consolidating more expensive debt. If you are consolidating debt, add up what you pay now across all your balances. Then check that the new loan reduces the total cost, not just the monthly payment.
A sensible approach is to get soft-search quotes from more than one lender, compare the personal APR and total repayable for the same amount and term, check the early repayment terms, and only then make one full application.
Frequently asked questions about Zopa loans
Does checking my rate with Zopa affect my credit score?
No. The rate check uses a soft search, which other lenders cannot see. A hard search is only recorded if you go ahead with a full application and are approved.
How much can I borrow with Zopa?
Zopa states a range of £1,000 to £50,000, over one to seven years. How much you are offered depends on your income, outgoings and credit history.
Why is my rate different from the advertised APR?
The representative APR is an example rate that only a share of successful applicants receive. Your personal APR is based on your own credit profile, the amount you borrow and the term you choose.
What happens if I am declined?
Avoid applying to lots of lenders straight away. Check your credit report for errors, look at what may have affected the decision, such as high existing debt, and use soft-search tools before your next full application.
Can I compare Zopa with Tesco Bank and Barclays loans?
Yes. Get a personalised quote from each lender for the same amount and term, then compare the personal APR, the total repayable and the early repayment terms.
Photo: AymaneJed / Pixabay